
Reverse Mortgage When Aging Homeowner Discovers Hidden Defects: Seller Non-Disclosure Remediation
Fund major repairs when aging homeowner discovers undisclosed property defects. Reverse mortgage for remediation costs in Ontario.
Did your aging parent recently discover major hidden defects in their home—structural issues, environmental hazards, or mechanical failures—that the previous owner failed to disclose? Home purchase disasters often unfold years after purchase: foundation cracks that reveal water intrusion, hidden mold in walls, unpermitted renovations creating code violations, underground storage tank contamination, or failing infrastructure (roof, plumbing, electrical). When these defects surface, aging homeowners face anguishing choices: expensive remediation, potential legal action against prior owners (costly, uncertain outcome), or home value collapse. A reverse mortgage can provide immediate funding for essential remediation while you navigate the legal and financial complexities of seller non-disclosure.
The Hidden Defects Problem: Prevalence and Financial Impact
Approximately 15-20% of Ontario residential property sales involve later-discovered defects that weren't disclosed during purchase. Many of these defects remain hidden for years (even decades) because they're structural, environmental, or behind walls—only surfacing when routine maintenance reveals them.
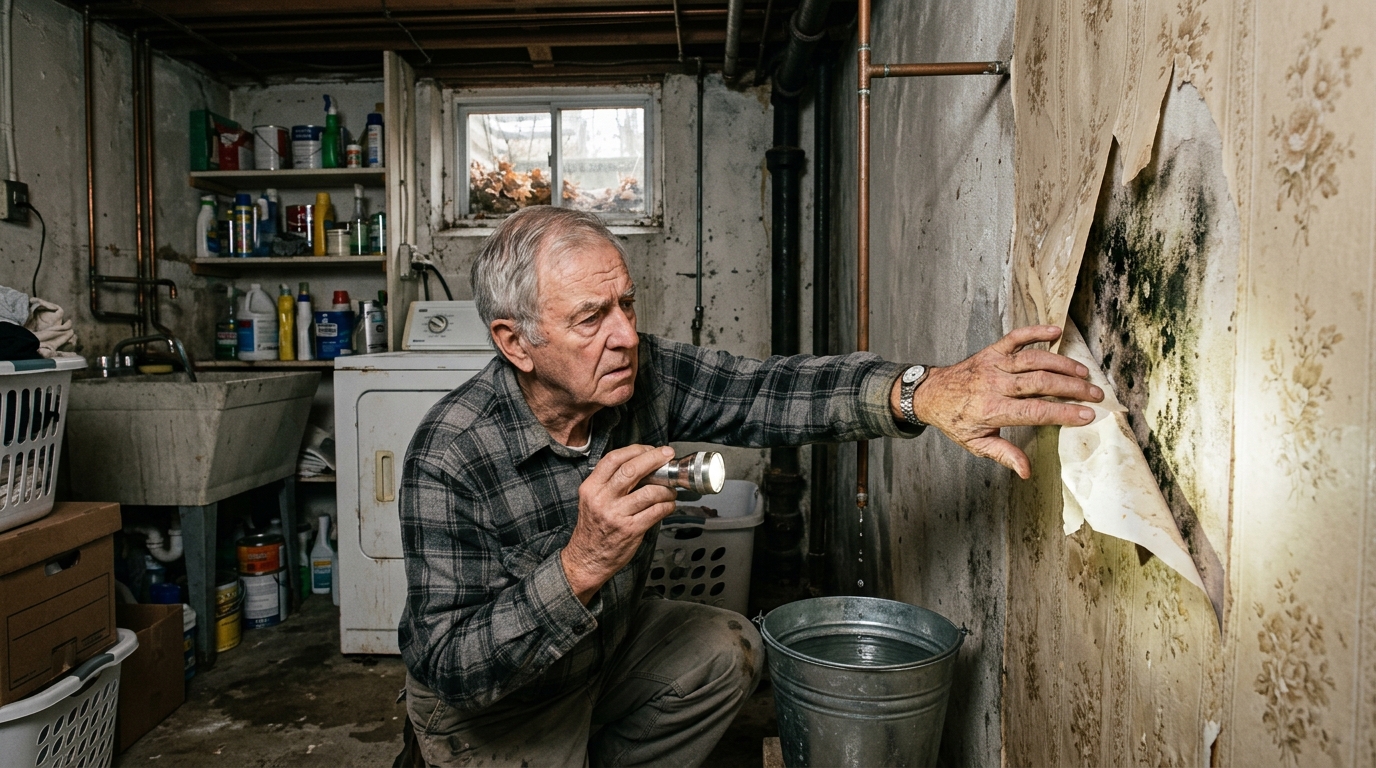
Common hidden defects include:
- Structural/foundation issues: Cracks, water intrusion, settling, beam rot (discovery: home inspection, water damage, or insurance claim)
- Mold and environmental hazards: Hidden mold in walls/attic, asbestos, lead paint, radon (discovery: health symptoms, inspection, or renovation)
- Unpermitted renovations: Room additions, basement finishing, electrical/plumbing work done without permits (discovery: home inspection, insurance claim, or when selling)
- Environmental contamination: Underground oil tank leaks, soil contamination, neighboring industrial pollution (discovery: environmental assessment, remediation tests)
- Mechanical system failures: Roof nearing end-of-life, failing HVAC systems, galvanized plumbing (discovery: system failure, inspection, or insurance assessment)
- Water intrusion and moisture problems: Chronic basement leaking, foundation cracks, improper grading (discovery: water damage during heavy rain, mold growth)
Financial impact of undisclosed defects: $10,000–$150,000+ depending on severity.
| Defect Type | Typical Remediation Cost | Detection Timeline | Legal Recourse |
|---|---|---|---|
| Foundation crack/water intrusion repair | $15,000–$50,000 | 2–10 years post-purchase | Possible (disclosure liability) |
| Mold remediation (walls/attic) | $5,000–$30,000 | 3–8 years post-purchase | Possible (health hazard liability) |
| Roof replacement (undisclosed age) | $8,000–$15,000 | 5–15 years post-purchase | Limited (roof aging is visible) |
| Electrical/plumbing code violation fixing | $8,000–$25,000 | 2–10 years post-purchase | Possible (code violation liability) |
| Underground tank removal/contamination cleanup | $20,000–$100,000+ | 5–20 years post-purchase | Possible (environmental liability) |
| HVAC system replacement (hidden age/condition) | $4,000–$8,000 | 5–15 years post-purchase | Limited (systems have visible age) |
Legal Liability and Disclosure in Ontario
Ontario law requires sellers to disclose known material defects. Failure to disclose is a legal violation, but the practical reality is complicated:
According to the Law Society of Ontario and the Real Estate Council of Ontario, sellers must disclose defects they know about, BUT the burden is on the buyer to prove the seller knew about the defect and failed to disclose. Once 2-5 years pass, proving knowledge becomes difficult, and legal action becomes expensive.
Practical legal scenario:
- You discover mold in walls 7 years post-purchase
- Previous owner claims they didn't know it was there
- You hire environmental lawyer: $3,000–$8,000 in legal costs
- You pursue civil case: $15,000–$50,000+ in litigation costs (over 18–24 months)
- You win: Previous owner is liable, but often judgment is uncollectible (they moved, assets gone, bankruptcy)
- You lose or settle: You paid legal costs with no recovery
Result: Many aging homeowners face massive remediation costs with no viable legal recourse.
How a Reverse Mortgage Provides Emergency Remediation Funding
Rather than pursuing expensive, uncertain legal action, a reverse mortgage can immediately fund essential repairs:
Strategy 1: Emergency Remediation (Weeks 1–8)
When a defect is discovered that poses safety or health risks:
- Immediate stabilization: Waterproofing foundation crack, sealing mold-infected areas, isolating electrical hazards ($2,000–$8,000)
- Professional assessment: Structural engineer, environmental consultant, or code inspector to quantify scope ($400–$1,500)
- Initial remediation phase: Repair most urgent components to ensure safety and prevent escalation ($5,000–$20,000)
Total emergency draw: $8,000–$30,000 (weeks 1–8).
Strategy 2: Phased Remediation (Months 2–12)
Once emergency phase is complete, implement comprehensive remediation:
- Phase 1 (Months 2–4): Address health hazards (mold remediation, environmental cleanup)
- Phase 2 (Months 4–8): Structural repairs (foundation work, water intrusion prevention)
- Phase 3 (Months 8–12): Code compliance (electrical, plumbing, permit work)
Total phased remediation: $20,000–$80,000 depending on defect scope.
Strategy 3: Legal Support While Pursuing Seller Liability (Months 1+)
Simultaneously fund legal investigation and potential lawsuit:
- Real estate lawyer consultation: Initial assessment of disclosure liability ($1,500–$3,000)
- Environmental/structural expert reports: Professional documentation of defect and remediation necessity ($2,000–$5,000)
- Litigation funding: If pursuing case, reverse mortgage funds legal expenses while awaiting judgment ($10,000–$50,000+)
Total legal strategy draw: $15,000–$60,000 over 12–36 months.
Real-Life Scenario: Mold Discovery and Non-Disclosure
Robert's Story: Robert, 71, purchased his Ontario home 8 years ago for $425,000. It was his retirement home, and he planned to age in place. During a kitchen renovation (year 8), contractors discovered extensive black mold behind walls—originating from a roof leak the previous owner had never disclosed.
Remediation assessment:
- Remove affected drywall and insulation: $3,200
- Remediate mold: $5,800
- Replace structural components: $8,000
- New roof (the actual underlying cause): $12,000
- Preventive measures (improved ventilation): $3,000
Total remediation cost: $32,000.
Robert's situation:
- Retired with $52,000/year fixed pension income
- Home was his largest asset (~$480,000 current value, now declining due to mold knowledge)
- Could not afford $32,000 remediation from income
- Sale was not an option (who buys a mold-damaged home? value collapse to $380,000–$420,000)
Reverse mortgage solution:
- Initial consultation with real estate lawyer (funded by RM): Assessment showed possible disclosure liability, but litigation would cost $20,000–$30,000 with uncertain outcome
- Immediate remediation funding (reverse mortgage line of credit): Drew $32,000 over 6 weeks to complete all remediation
- Continued living in home: Post-remediation, home is safe, healthy, and marketable again
- Potential recovery: Simultaneously, lawyer sent formal demand letter to previous owner (potential settlement, though unlikely)
| Year | Robert's Situation | RM Draw | Reverse Mortgage Balance |
|---|---|---|---|
| Year 8 (discovery) | Mold found; remediation decision | $32,000 | $32,000 |
| Year 9 | Home fully remediated; living peacefully | $0 | $32,000 + interest (~$1,500) |
| Year 10+ | Aging safely at home; mold resolved | $0 | Declining balance as interest-only payments or as-drawn |
Key outcome: Robert remained in his home, the mold was fully remediated, and the property was restored to safe/marketable condition. Total reverse mortgage cost: ~$1,500/year in interest on the $32,000 balance—far cheaper than selling (realtor fees 5-7% = $21,000–$29,400), moving costs, or purchasing an alternative property at current prices.
Documenting Defects for Legal Action
If pursuing seller non-disclosure claims, comprehensive documentation is essential:
| Documentation | Purpose | Cost | Timing |
|---|---|---|---|
| Professional inspection reports | Establish defect existed; scope of damage | $400–$1,500 | Immediately upon discovery |
| Engineer/specialist assessment | Quantify remediation necessity; cost estimates | $800–$2,500 | Within 2–4 weeks |
| Remediation quotes (multiple) | Establish fair market repair costs | $0–$200 (3-5 quotes) | Within 4 weeks |
| Photographic/video documentation | Visual evidence of defect extent | $0 (DIY) or $500–$1,500 (professional) | At discovery; during remediation |
| Legal demand letter | Formal notification to prior owner; discovery opportunity | $1,500–$3,000 (lawyer) | 4–8 weeks post-discovery |
| Litigation preparation | If case proceeds, expert depositions, court documents | $15,000–$50,000+ | 6–24 months if litigating |
A reverse mortgage can fund professional documentation, expert reports, and legal costs simultaneously while remediation is underway.
Coordinating Reverse Mortgage with Home Insurance Claims
Important: Some defects trigger homeowner's insurance claims (water intrusion, sudden system failures). Others don't (undisclosed pre-existing conditions). Check with your insurance before assuming coverage:
- Water damage from roof leak (if roof failure is sudden): Possible insurance coverage; expect $500–$2,000 deductible
- Mold remediation: Often NOT covered by standard homeowner's insurance; may require separate rider
- Structural damage (foundation, settling): Generally NOT covered (considered wear-and-tear)
- Environmental contamination (soil, underground tank): NOT covered by homeowner's insurance; environmental remediation insurance (specialty) may apply
Strategy: File insurance claims for covered items first; use reverse mortgage for non-covered remediation.
Key Takeaways
- 15-20% of Ontario home sales involve later-discovered defects not disclosed at purchase
- Remediation costs: $10,000–$150,000+ depending on defect type and severity
- Legal action against prior owner is expensive ($20,000–$60,000+ in litigation costs) with uncertain outcome
- Reverse mortgage provides immediate remediation funding without waiting for legal resolution
- Phased remediation approach (emergency → comprehensive → prevention) minimizes costs
- Professional assessment and documentation essential for both safety and potential legal recovery
- Coordinating with homeowner's insurance may offset some reverse mortgage draw needed
- Aging homeowners can remain safely in homes post-remediation using reverse mortgage funding
Frequently Asked Questions
If I discover a hidden defect and pursue legal action, can I also use reverse mortgage funds for remediation?
Yes. Most attorneys recommend remediating immediately (for safety, health, and property protection) while pursuing legal claims separately. The reverse mortgage funds immediate needs; legal recovery (if successful) reduces the total debt burden later.
Does discovering a hidden defect reduce my home's value permanently?
Not if fully remediated. A home with documented mold remediation (professional removal, inspection clearance) typically recovers most value. Undisclosed, unremediateddefects permanently depress value. This is why immediate remediation (via reverse mortgage) is strategically important.
Can I sue the real estate agent or home inspector who missed the defect at purchase?
Possibly. If the inspector failed to identify a defect that professional inspection should have caught, you may have a claim against the inspection company or realtor. This is separate from seller liability. Consult a real estate lawyer to evaluate all liability paths.
What if the remediation cost is very high ($80,000–$100,000+) and my reverse mortgage doesn't provide enough equity?
For large defects, you may face a hard choice: complete remediation, partial remediation with ongoing management, or sale (accepting lower price). Discuss with reverse mortgage lender about maximum available based on home equity. Litigating seller liability may be necessary.
Does a reverse mortgage for remediation affect my ability to sell the home later?
No. Once remediated and documented, the property is restored. When selling, disclose the past defect and remediation; buyers see professional remediation as protective (better than undisclosed ongoing problems). Title is clear; sale is straightforward.
Can I use reverse mortgage funds to fund radon testing and mitigation?
Yes. Radon (radioactive gas) is a serious health hazard. Reverse mortgage can fund testing ($200–$400) and mitigation systems ($800–$2,500). This is considered health-related home modification and is legitimate use of reverse mortgage funds.
Discovering hidden defects years after purchase is devastating, but a reverse mortgage can provide the immediate funding to remediate safely and completely—allowing you to age in place in a home that's no longer a health risk or financial albatross.
Ready to Learn More?
Find out exactly how much you could unlock from your home — free and no obligation.
Related Articles
Reverse Mortgage When Longtime Live-In Caregiver Retires or Becomes Ill: Care Restructuring
Emergency financial strategy when aging parent's live-in caregiver must leave. Reverse mortgage for sudden care system overhaul in Ontario.
Read →Reverse Mortgage for Managing Escalating Prescription Drug Costs: Polypharmacy in Aging
Learn how a reverse mortgage can fund rising medication costs when aging parents on multiple drugs face affordability crises in Ontario healthcare.
Read →Reverse Mortgage for Home Environmental Modifications: Managing Respiratory Hypersensitivity in Aging
Fund specialized HVAC, air quality, and ventilation systems when aging parent has respiratory sensitivity. Reverse mortgage for environmental health in Ontario.
Read →